Global IoT News of the Week: Smart Buildings, Edge AI, and Evolving Ecosystem Standards for August 18, 2023

The rapid convergence of artificial intelligence, edge computing, and strict regulatory frameworks dominated the Internet of Things (IoT) landscape during the third week of August 2023. Across the technology sector, manufacturers, infrastructure providers, and enterprise operators faced mounting pressures to enhance hardware reliability, embrace advanced machine learning capabilities locally, and navigate the fragmented realities of emerging smart home interoperability standards.
From significant venture capital injections into sustainable building technology to regulatory-driven infrastructure upgrades within the electric vehicle charging sector, this week’s developments underscore a maturing IoT ecosystem. Industry stakeholders are increasingly prioritizing operational resilience, power efficiency, and data privacy over mere novelty, setting a rigorous standard for the remainder of the hardware and software development cycle.
Enterprise IoT and Sustainable Infrastructure: Verdigris Secures $10 Million
In the enterprise technology sphere, intelligent building platform Verdigris successfully closed a $10 million funding round. The financing, announced in mid-August 2023, was co-led by venture capital firms DCVC and Solea Energy. This capital injection arrives at a challenging macroeconomic juncture for venture-backed enterprise software and hardware startups, signaling continued investor confidence in technologies that demonstrably reduce commercial energy consumption.
Founded over a decade ago, Verdigris specializes in deploying artificial intelligence and Internet of Things sensors to monitor and optimize commercial heating, ventilation, and air conditioning (HVAC) systems. Large commercial buildings remain notorious energy consumers, often accounting for a significant percentage of urban carbon emissions. By utilizing high-frequency power meters combined with cloud-based machine learning algorithms, the company’s platform detects electrical anomalies, predicts mechanical failures, and autonomously optimizes HVAC workflows to minimize utility waste.
Industry analysts note that the renewed market hype surrounding generative and applied artificial intelligence has provided a helpful tailwind for B2B climate tech companies. However, unlike consumer-facing applications, platforms like Verdigris rely on deep, hard-earned domain expertise in electrical engineering and building management systems. The newly acquired capital will be deployed to accelerate sales cycles, expand market reach, and refine predictive maintenance features designed to help real estate operators meet increasingly stringent municipal and federal energy efficiency mandates.
Edge Computing and Hardware Acquisitions: Nordic Semiconductor Acquires Atlazo IP
The intersection of artificial intelligence and low-power hardware advanced significantly with Nordic Semiconductor’s strategic acquisition of intellectual property from Atlazo. Based in San Diego, California, Atlazo specialized in the design and development of ultra-low-power microcontrollers (MCUs) optimized specifically for machine learning and edge computing workloads.
Nordic Semiconductor, a global leader in low-power wireless connectivity chips designed for Bluetooth, Wi-Fi, and cellular IoT applications, structured the transaction as a targeted asset purchase. According to executive leadership at Nordic, the integration of Atlazo’s advanced IP will take place over a projected timeline of 12 to 18 months, ultimately allowing the company to embed sophisticated on-device machine learning capabilities directly into its upcoming silicon portfolios.
The acquisition reflects a broader, industry-wide migration away from cloud-dependent processing toward edge AI. Transmitting raw sensor data continuously to centralized cloud servers consumes substantial wireless bandwidth, drains battery reserves rapidly, and introduces privacy vulnerabilities. By processing machine learning inferences locally on resource-constrained microcontrollers, IoT devices can interpret sensor data instantaneously, reduce power consumption, and maintain functionality even in the absence of internet connectivity. Market researchers project that the demand for tiny machine learning (TinyML) hardware will expand exponentially as smart agriculture, industrial predictive maintenance, and wearable health tech sectors mature.
Public Infrastructure and Compliance: ChargePoint Establishes National Network Operations Center
In the electric vehicle (EV) infrastructure sector, charging network operator ChargePoint announced the establishment of a centralized Network Operations Center (NOC) to monitor the operational health of its vast footprint, which encompasses approximately 243,000 charging ports across the United States and Europe.
The strategic shift toward centralized, telecommunications-style network monitoring comes in direct response to evolving federal and regional regulations. Recent government funding initiatives aimed at accelerating EV adoption have introduced mandatory uptime requirements for publicly funded charging infrastructure. Historically, public EV chargers have suffered from inconsistent reliability, frequently plagued by software crashes, unresponsive hardware, and payment processing failures that frustrate consumers.
By adopting a traditional enterprise network monitoring model—akin to those utilized by major telecommunications carriers—ChargePoint aims to proactively identify and remediate hardware malfunctions before end-users experience them. Industry observers have pointed out that proactive monitoring should arguably have been a foundational pillar of the commercial EV charging business model from its inception. Nevertheless, the investment highlights an overarching trend across the connected device economy: as IoT deployments transition from experimental novelties to critical public infrastructure, operators are being held to rigorous enterprise-grade reliability standards.
Smart Home Ecosystems and Subscription Models: Shelly Introduces Energy Management Tiers
Consumer smart home manufacturers continue to experiment with business models designed to supplement transactional hardware sales with predictable, recurring revenue streams. European smart home automation brand Shelly launched a premium software subscription tier tailored specifically for advanced energy management.
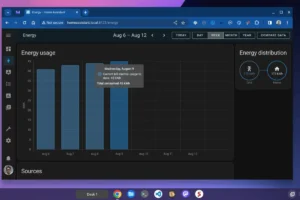
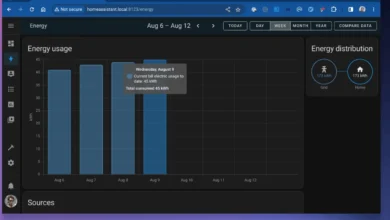
Priced at approximately €3.99 ($4.34) per month, the subscription service is targeted at consumers seeking granular insights into their domestic electricity consumption. Subscribers gain access to automated notification systems that alert users when household appliances are left running, flag anomalous power spikes or drops, and provide detailed analytical tracking across connected devices. Shelly claims that utilizing the platform’s diagnostic capabilities can help households reduce their monthly electricity bills by up to 18%.
The introduction of subscription services within the smart home sector remains a contentious topic among consumers accustomed to purchasing standalone hardware with lifetime local functionality. However, manufacturers argue that maintaining secure cloud servers, continuously updating software to patch cybersecurity vulnerabilities, and developing complex analytical algorithms require ongoing operational expenditures that cannot be sustained solely through one-time hardware purchases.
Interoperability and Standards Fragmentation: Aqara T1 LED Strip and the Matter Dilemma
The ongoing evolution of the smart home interoperability standard, Matter, continues to present consumers and device manufacturers with complex engineering compromises. Aqara expanded its product lineup with the launch of the RGB Smart Light Strip T1, retailing at $49.95.
While the new light strip natively supports the multi-ecosystem Matter standard—allowing it to integrate seamlessly with platforms developed by Apple, Amazon, and Google—adopting Matter introduces functional limitations. Specifically, the current Matter specification does not support Adaptive Lighting, an automated feature that dynamically adjusts color temperature and brightness levels throughout the day based on circadian rhythms. To utilize Adaptive Lighting on the T1 light strip, users must bypass Matter entirely and connect the device via Zigbee using a proprietary Aqara hub.
This design dilemma exemplifies the broader growing pains experienced by the smart home industry during the widespread rollout of Matter. While the protocol successfully achieves cross-platform device discovery and local communication, it often acts as a lowest-common-denominator standard, occasionally forcing users to sacrifice advanced, vendor-specific functionalities in exchange for universal interoperability.
Market Speculation and Corporate Restructuring: Alphabet and the Google Nest Division
Financial markets and technology analysts closely monitored corporate restructuring signals originating from Alphabet, Google’s parent corporation. Recent reports from financial publications indicated that Verily, one of Alphabet’s experimental "Other Bets" subsidiaries, is actively separating its corporate infrastructure services in preparation for a potential corporate spin-out by late 2024.
The anticipated movement of Verily has ignited speculation regarding the future organizational structure of other Alphabet entities, most notably the Google Nest smart home division. Under the strategic direction of Alphabet President and Chief Investment Officer Ruth Porat, the conglomerate has increasingly focused on fiscal discipline, cost optimization, and the critical evaluation or divestment of underperforming business units.
Although any potential spin-out of the Google Nest ecosystem remains speculative, industry analysts suggest that such a corporate maneuver would send shockwaves through the consumer IoT market. Nest holds a foundational position in the global smart home ecosystem, encompassing thermostats, security cameras, smart displays, and software integrations. A structural independence from Alphabet could grant the division greater operational agility, though it would simultaneously raise questions regarding long-term software support, ecosystem integration, and hardware roadmaps.
Industry Outlook and Regulatory Trajectory
The developments of mid-August 2023 illustrate an IoT industry transitioning decisively into a phase of consolidation, operational accountability, and regulatory compliance. Whether through enterprise software securing vital funding in a cautious financial climate, semiconductor firms consolidating edge AI intellectual property, or infrastructure providers adopting rigorous network monitoring paradigms, the emphasis has shifted firmly from rapid expansion to sustained performance.
As regulatory bodies enforce stricter cybersecurity, uptime, and energy efficiency mandates, manufacturers can no longer rely on superficial feature sets. The ability to deliver reliable, secure, and locally intelligent connected systems will ultimately dictate market leadership as the Internet of Things continues to embed itself deeper into industrial infrastructure and daily consumer life.