The Hardware Industry Pivot: Consumer Tech Takes a Backseat as Manufacturers Chase the Lucrative AI Infrastructure Boom

The global technology hardware landscape is undergoing a profound structural transformation, characterized by a decisive pivot among major manufacturers away from consumer-grade components and toward enterprise-level artificial intelligence infrastructure. This industry-wide redirection of capital, research and development, and manufacturing capacity has sparked intense debate among industry analysts, long-time technology enthusiasts, and economists. While corporate stakeholders champion the unprecedented growth driven by generative artificial intelligence and data center expansion, critics and seasoned consumers express growing frustration over the neglect of traditional consumer markets, rising hardware costs, and the rapid pace of technological consolidation.
This shift represents one of the most significant realignments in the history of the modern technology sector. For decades, consumer electronics—ranging from high-end desktop graphics processing units and custom personal computer components to affordable laptops and mobile devices—served as the primary engine of innovation and revenue for semiconductor giants and hardware manufacturers. Today, however, the gravitational pull of enterprise artificial intelligence contracts has fundamentally altered corporate priorities.
The Genesis of the Infrastructure Shift
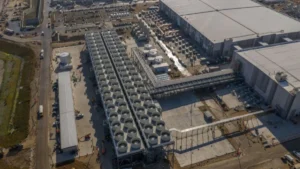
To understand the current state of the hardware market, it is necessary to examine the convergence of technological advancements and market demands that catalyzed the artificial intelligence boom. The modern AI infrastructure era gained monumental momentum in late 2022 with the public deployment of advanced large language models. These computational models required unprecedented amounts of processing power, memory bandwidth, and energy storage, instantly transforming standard data centers into high-performance artificial intelligence factories.
Throughout 2023 and 2024, semiconductor manufacturers realized that profit margins on enterprise-grade accelerators, specialized graphics processing units for server farms, and high-density networking equipment vastly outstripped those available in the consumer hardware sector. Consequently, capital expenditure budgets shifted dramatically. Research and development teams that traditionally focused on improving power efficiency, thermal performance, and cost-effectiveness for everyday users were reassigned to optimize architectures for massive, rack-scale enterprise deployments.
Industry observers note that this transition has created a severe supply-demand imbalance in the consumer space. Component shortages, extended product lifecycles, and escalating retail prices have become standard across major hardware categories. For enthusiasts who have relied on traditional enthusiast platforms for decades, the current market environment feels increasingly alienating, as mainstream technology publications and manufacturer announcements are overwhelmingly dominated by enterprise metrics, tensor core optimizations, and hyperscale data center construction projects.
Chronology of Market Realignment
The progression from a consumer-centric technology market to an enterprise-dominated artificial intelligence ecosystem can be traced through several key phases over the past decade:
- 2015–2019 (Foundational Growth): Deep learning research accelerates, leading to the initial adoption of specialized hardware accelerators primarily within elite research institutions and major cloud service providers. Consumer hardware remains the dominant revenue driver for semiconductor fabrication plants.
- 2020–2022 (The Pandemic Catalyst): Global supply chain disruptions strain consumer electronics manufacturing. Concurrently, early large language models demonstrate commercial viability, prompting forward-looking technology firms to quietly stockpile high-performance computing components.
- Late 2022 (The Generative AI Tipping Point): The public release of generative text and image models creates an immediate, insatiable global demand for specialized artificial intelligence infrastructure. Hyperscale cloud providers announce multi-billion-dollar investments in data center expansion.
- 2023–2024 (The Great Pivot): Major hardware manufacturers officially restructure their product roadmaps. Production lines are converted to prioritize enterprise accelerators over consumer graphics cards and client-tier processors. Profit margins soar for chipmakers, while retail prices for consumer hardware climb significantly.
- 2025 and Beyond (Entrenchment and Scrutiny): Enterprise artificial intelligence spending reaches historic highs, while consumer advocates and industry analysts increasingly question the long-term sustainability of the current market trajectory, raising concerns about economic exposure and regulatory oversight.
Economic Implications and Market Vulnerabilities
The heavy concentration of capital within the artificial intelligence sector has introduced systemic vulnerabilities into the broader economy. Financial analysts have increasingly drawn parallels between the current artificial intelligence infrastructure buildout and historical technology bubbles, most notably the dot-com boom of the late 1990s and early 2000s.
Economic data compiled by major financial institutions indicates that capital expenditures by the world’s largest technology conglomerates on data center infrastructure and artificial intelligence hardware have reached unprecedented levels. While these investments generate immediate revenue for semiconductor fabrication facilities and specialized hardware designers, questions persist regarding the ultimate return on investment for enterprise clients deploying these technologies.
Economists specializing in the technology sector point out two primary risks associated with the current trajectory. First, if enterprise adoption of artificial intelligence fails to generate the revenue required to justify the massive capital outlays, a sudden correction could occur. When market bubbles of this magnitude eventually deflate, the subsequent contraction tends to be rapid, resulting in sharp reductions in corporate spending, workforce downsizing across the technology sector, and localized economic downturns.
Second, the diversion of manufacturing capacity away from consumer goods risks alienating the broader consumer base that sustained the technology industry through its formative decades. When entry-level and mid-range hardware becomes prohibitively expensive or difficult to source, consumer participation in the digital economy can stagnate, creating a widening chasm between hyper-funded enterprise capabilities and stagnant consumer purchasing power.
The Horizon: Robotics, Automation, and Corporate Governance
As the artificial intelligence industry matures, corporate strategy is increasingly looking beyond software-based models toward physical integration, specifically through robotics and autonomous systems. Industry leaders frequently position humanoid and specialized industrial robots as the ultimate evolution of artificial intelligence, arguing that true intelligence requires physical embodiment to interact with, learn from, and manipulate the physical world.
This strategic direction, however, introduces complex socioeconomic and ethical challenges. The integration of advanced artificial intelligence into robotic systems designed for manual labor carries significant implications for global labor markets. While corporate entities emphasize efficiency gains, cost reductions, and productivity enhancements, labor economists warn of potential large-scale displacement in manufacturing, logistics, warehousing, and service sectors.
Furthermore, the rapid pace of development has intensified debates surrounding corporate governance and regulatory oversight. Critics argue that technology companies are deploying complex, autonomous systems with insufficient regard for long-term societal consequences, safety protocols, and accountability frameworks. Unlike traditional software applications, autonomous robotic systems operating in physical environments possess the capacity to cause tangible, real-world harm if system failures occur.
As a result, policymakers, ethicists, and consumer advocacy groups are increasingly calling for formalized regulatory frameworks to govern the deployment of advanced artificial intelligence and autonomous hardware. These proposals generally advocate for rigorous safety testing, transparent algorithmic auditing, and mechanisms to ensure corporate accountability for autonomous actions.
Industry Response and Stakeholder Perspectives
Representatives from major hardware manufacturers and artificial intelligence firms maintain that the ongoing strategic pivot is both necessary and beneficial for global technological progress. Corporate statements consistently emphasize that the computational breakthroughs achieved in data centers today will eventually trickle down to consumer devices, enabling smarter operating systems, enhanced personal productivity tools, and more efficient hardware architectures in the future.
Furthermore, industry proponents argue that the race for artificial intelligence supremacy is a geopolitical imperative, with nations vying for technological leadership in critical infrastructure. From this perspective, the diversion of resources away from consumer-grade hardware is a rational response to a once-in-a-generation technological revolution that will define the global economy for the next century.
Conversely, consumer advocates and independent technology analysts urge a more balanced approach. They contend that sustainable industry growth requires maintaining a healthy equilibrium between enterprise innovation and accessible consumer technology. Without deliberate efforts to protect consumer interests, foster fair market competition, and manage the broader societal impacts of rapid automation, the current artificial intelligence boom risks leaving a legacy of economic fragility and consumer disenfranchisement.
As the market continues to evolve, the tension between hyper-accelerated enterprise investment and traditional consumer needs will remain a defining characteristic of the global technology landscape. Whether the current trajectory results in a sustainable technological renaissance or a disruptive market correction, the decisions made by hardware manufacturers today will profoundly shape the economic and social structures of the decades to come.