Samsung Electronics Mulls Major Galaxy A-Series Production Cuts Amid Surging Component and Memory Prices

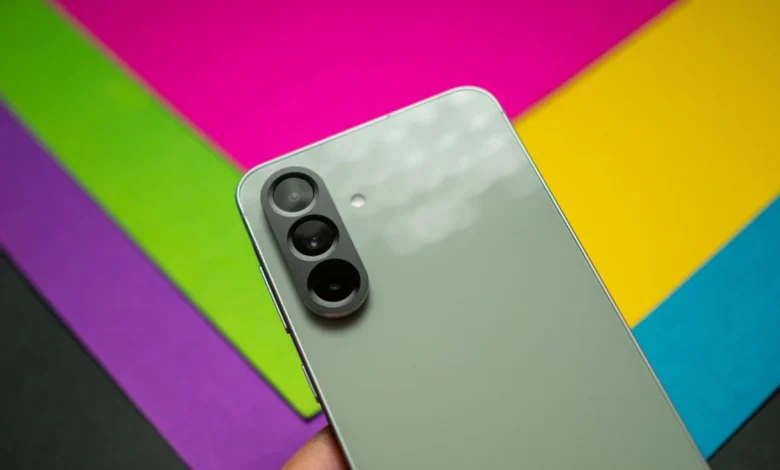
Samsung Electronics is reportedly preparing to significantly scale back the production of its high-volume, budget-friendly Galaxy A smartphone lineup as soaring component costs place unprecedented financial pressure on the tech giant’s mobile division. According to recent reports originating from South Korean industry publications like ETNews, Samsung is contemplating a roughly 20 percent reduction in Galaxy A-series manufacturing output during the fourth quarter, a move that could potentially result in millions fewer units reaching the global market than initially projected.
This strategic pivot underscores a broader, industry-wide crisis: the escalating cost of crucial semiconductor hardware, particularly memory chips, is fundamentally reshaping the economics of mass-market consumer electronics. While Samsung has not yet officially confirmed these production adjustments, industry analysts are closely monitoring the situation. If verified, the move could signal a profound strategic shift for the world’s leading smartphone manufacturer by volume, altering how budget-conscious consumers access mobile technology and potentially impacting Samsung’s fierce, ongoing rivalry with competitors such as Apple and major Chinese manufacturers.
The Roots of the Crisis: Exploding Memory and Component Costs
At the heart of Samsung’s production dilemma lies a severe macroeconomic and supply chain squeeze centered on memory chip pricing. In recent quarters, the cost of dynamic random-access memory (DRAM) and NAND flash storage has skyrocketed, driven by surging global demand for high-performance AI hardware. Semiconductor manufacturers have increasingly redirected their fabrication lines and capital investments toward specialized, high-margin AI accelerators and enterprise-grade infrastructure components. Consequently, the supply of standard consumer-grade memory components has tightened dramatically, driving up procurement costs for device makers.
For flagship devices such as the Samsung Galaxy S series or the foldable Galaxy Z lineup, high component costs can often be absorbed or passed directly onto consumers, given the premium price points and healthy profit margins associated with these devices. However, the mathematics of the budget and mid-range smartphone segments are entirely different.
In affordable handsets, the cost of memory chips alone can account for more than half of the total bill of materials (BoM). Beyond semiconductors, other fundamental components—including printed circuit boards (PCBs) and multilayer ceramic capacitors (MLCCs)—have also seen price increases as suppliers prioritize more lucrative technology sectors. Producing entry-level and mid-range devices has thus become an increasingly low-margin, or even unprofitable, endeavor. For a publicly traded company accountable to shareholders, continuing to manufacture millions of devices that yield minimal financial return is an unsustainable business model, making production cutbacks an economically rational, albeit difficult, decision.
Strategic Realignment: Prioritizing Margins Over Volume
The Galaxy A series is far from a marginal product line for Samsung; it serves as the cornerstone of the company’s global market share strategy. Historically accounting for roughly 70 percent of Samsung’s total annual smartphone shipments, the Galaxy A lineup has been instrumental in maintaining the company’s competitive edge in developing markets and serving as a volume counterweight to Apple’s dominance in the premium sector.
By scaling back Galaxy A production by an estimated 20 percent in the fourth quarter—translating to roughly 10 million fewer devices annually—and eyeing further production cuts exceeding 10 percent heading into subsequent years, Samsung is executing a calculated retreat from pure volume dominance in favor of protected profit margins. Industry reports indicate that Samsung is deliberately reallocating its scarce, high-cost component inventory toward its higher-margin flagships. Rather than flooding the market with low-margin handsets that generate thin profits, the corporation appears willing to accept lower overall shipment volumes to safeguard its bottom line.
This reported strategic adjustment follows earlier rumors from late 2025 and early 2026, which suggested that Samsung might reduce its overall smartphone production targets by 20 to 30 percent for the fourth quarter. These cumulative reports indicate that initial manufacturing targets—which aimed for approximately 270 million units annually—are being aggressively reassessed as the memory market shows no immediate signs of returning to historical pricing lows.
Chronology of Events and Industry Precedents
To understand the current predicament, it is necessary to examine the timeline of pressures facing the consumer electronics sector over the past several years:
- Late 2024 to Early 2025: Initial signs of a memory market recovery emerge as global artificial intelligence deployment accelerates. Demand for high-bandwidth memory (HBM) and enterprise data center chips begins to outpace fab capacity.
- Mid-2025: Component suppliers gradually shift manufacturing priorities toward AI-centric hardware, leading to tightening supplies of standard DRAM and NAND flash used in smartphones and personal computers.
- Late 2025: Tech industry analysts begin reporting anomalous spikes in component procurement costs, prompting early discussions among original equipment manufacturers (OEMs) regarding supply chain rationalization.
- Fourth Quarter 2025: Rumors surface that major smartphone makers are quietly trimming end-of-year shipment forecasts to mitigate exposure to inflated material costs.
- Early 2026: Reports from South Korean media outlets, including ETNews, detail specific plans by Samsung to slash Galaxy A-series manufacturing output by approximately 20 percent, signaling a structural shift in production philosophy.
- Present: Industry observers await official corporate confirmation while evaluating the broader implications for consumer pricing, product specifications, and global market share dynamics.
Implications for Consumers and Market Dynamics
For the everyday consumer, Samsung’s recalibration of its supply chain carries significant ramifications. Industry insiders have cautioned that these supply constraints and production cutbacks will likely filter down to the retail level. Future iterations of Galaxy A smartphones could debut at higher price points as Samsung attempts to offset the elevated cost of production. Alternatively, or concurrently, consumers may witness hardware downgrades—such as more modest display specifications or simplified camera systems—as manufacturers seek to maintain a palatable price ceiling by stripping out expensive components.
This dynamic creates a strategic vacuum in the budget and mid-range sectors. If Samsung pulls back on its high-volume affordable offerings, aggressive competitors stand ready to capture displaced consumers. Chinese smartphone manufacturers, known for operating on razor-thin hardware margins and maintaining agile domestic supply chains, could leverage this opportunity to expand their footprint in price-sensitive international markets across Latin America, Southeast Asia, India, and parts of Europe. Meanwhile, Apple continues to fortify its position in the premium segment, leaving Samsung to navigate a delicate tightrope: defending its profitability without surrendering its hard-won volume leadership to rivals.
As Samsung evaluates its long-term manufacturing blueprint, the overarching question remains whether the company can successfully pivot toward a value-over-volume model without permanently eroding its customer base in developing economies. With component pricing pressures expected to persist in the near term, the upcoming product cycles will serve as a critical test of Samsung’s market resilience and operational adaptability in a transformed technological landscape.
Related posts: