The True Cost of Localization: How EU Battery and EV Protection Policies Threaten to Raise Car Prices by Over €2,000

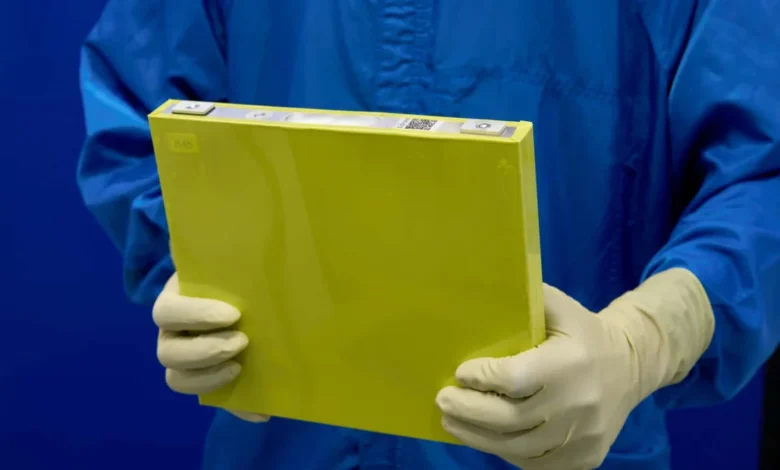
The European Union’s ambitious push toward automotive self-reliance and green industrial policy carries a substantial, hidden invoice for consumers. While policymakers in Brussels champion local manufacturing to safeguard domestic employment, reduce strategic dependence on external suppliers, and combat climate change, the economic realities of localized battery production reveal a significant financial burden. According to a comprehensive policy brief published by the Brussels-based economic think tank Bruegel, strict regulatory mandates requiring European-made electric vehicle (EV) batteries could inflate the final sticker price of new electric cars by an estimated €2,100.
As the European automotive sector grapples with declining production figures, fierce international competition, and shifting regulatory landscapes, the debate over how best to protect legacy automakers has reached a critical juncture. The core dilemma facing the continent is balancing the immediate necessity of affordable green mobility with the long-term geopolitical imperative of maintaining a viable European industrial base.
The Anatomy of the Cost Increase: Breaking Down the Battery Mandates
At the heart of Bruegel’s findings is a straightforward economic calculation regarding battery cell production costs within the European Union. Policymakers are increasingly favoring rules that mandate the use of locally manufactured battery cells to power the continent’s growing fleet of electric vehicles. However, establishing and operating battery gigafactories within Europe remains significantly more expensive than comparable operations in Asia, driven by higher labor costs, stricter environmental regulations, and more expensive energy inputs.
The Bruegel report estimates that requiring European-sourced battery cells could drive up production expenses by roughly €50 to €85 per kilowatt-hour (kWh). When applied to a standard mid-range electric vehicle equipped with a 60-kWh battery pack, the total cost differential scales dramatically. At the higher end of the estimate, this mandate alone accounts for an additional €2,100 per vehicle.
Furthermore, proposed regulatory requirements calling for the integration of low-carbon steel in vehicle manufacturing could tack on an additional €200 per unit. While the report notes that streamlining and simplifying the vehicle type-approval process could yield regulatory savings of roughly €61 per car for manufacturers, this modest administrative relief falls drastically short of offsetting the massive capital expenditure required to comply with localized material and battery mandates.
These increased production costs do not exist in a vacuum. Ultimately, automotive manufacturers operating on notoriously thin profit margins will be forced to decide how much of this financial burden to absorb and how much to pass along to the retail consumer. Industry analysts point out that entry-level vehicle segments will bear the brunt of these policies, threatening to price budget-conscious buyers out of the new EV market entirely and potentially slowing down the continent’s broader decarbonization trajectory.
Background Context: A Shifting Automotive Landscape in Europe
To understand the urgency driving Brussels to enact stringent industrial protections, one must examine the profound economic headwinds facing the European automotive sector over the past half-decade. The landscape of European car manufacturing has undergone a severe contraction since the onset of the decade. Statistical data indicates that EU vehicle production has plummeted by approximately 19% since 2019. Concurrently, consumer demand has cooled significantly, with buyers purchasing 2.2 million fewer new cars in 2025 than they did prior to the global health and economic disruptions of 2019.
Despite these contractions, the automotive industry remains a foundational pillar of the European economy, directly and indirectly employing roughly 14 million workers across the continent. Protecting this immense labor force is a primary political objective for EU lawmakers.
Yet, the competitive threat from abroad—most notably from China—has intensified at an alarming pace. The shifting dynamics of the global market were starkly highlighted at major industry showcases, such as the Paris Motor Show. There, Chinese automotive brands unveiled sophisticated electric vehicles featuring cutting-edge software architectures, luxurious gadget-filled interiors, and ultra-fast charging capabilities. In contrast, legacy European manufacturers frequently relied on their historical prestige, brand heritage, and traditional design language.
While established giants like BMW—with its upcoming Neue Klasse platforms like the iX3—and Mercedes-Benz—with its electric GLC offerings—have demonstrated that traditional European automakers possess the engineering prowess to fight back, a familiar badge no longer commands the automatic brand loyalty it once did in an increasingly tech-driven marketplace.
The Structural Struggles of European Battery Manufacturing
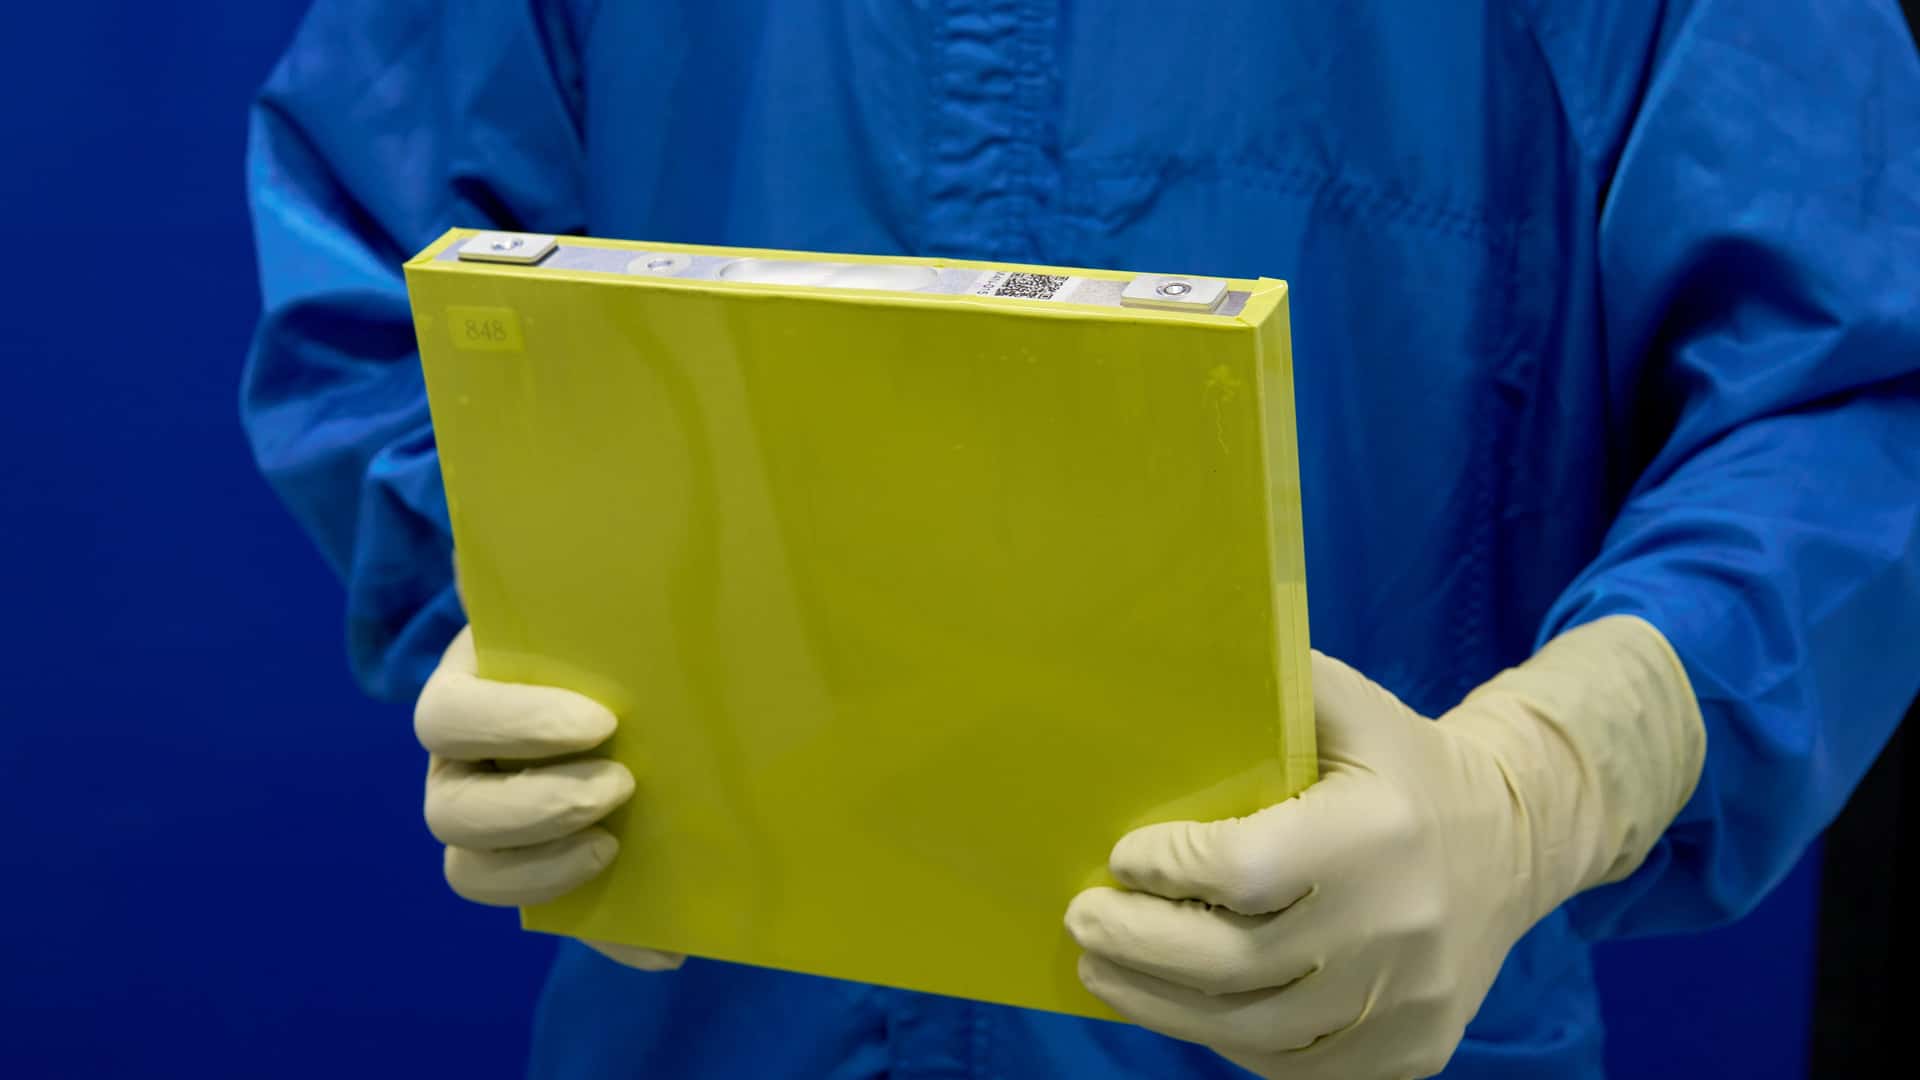
Establishing an independent European battery supply chain has proven to be an exceptionally arduous endeavor. Proponents of localization envisioned a rapid build-out of domestic gigafactories, but reality has dealt severe blows to these ambitions. High-profile setbacks have plagued the sector: the high-profile bankruptcy and restructuring struggles of Swedish battery pioneer Northvolt, Porsche’s strategic retreat from in-house battery manufacturing at Cellforce, and the shelving or scaling back of several Automotive Cells Company (ACC) factories underscore the immense difficulty of matching the economies of scale achieved by Chinese competitors.
Compounding this challenge is the reality that even batteries nominally manufactured within European borders frequently rely heavily on specialized manufacturing equipment, raw material processing expertise, and intellectual property originating from Asia.
Recognizing this foundational dependency, the authors of the Bruegel report argue that foreign investment and international partnerships are indispensable if Europe hopes to catch up. Data cited in the policy brief reveals that South Korean firms currently own 65% of Europe’s existing battery cell manufacturing capacity, while Chinese companies account for 55% of the capacity currently under development. Without this external industrial expertise and capital, European factories struggle to achieve commercial viability.
Trade Policy, Tariffs, and the Hybrid Boom
In an effort to shield domestic automakers from an influx of lower-cost vehicles, the European Commission implemented significant countervailing duties on fully electric vehicles imported from China, with tariff rates climbing as high as 35.3%. However, these targeted tariffs notably excluded plug-in hybrid electric vehicles (PHEVs).
This regulatory loophole triggered a swift market adaptation. Bruegel’s analysis highlights a distinct stagnation in battery-electric vehicle (BEV) imports from China, accompanied by a simultaneous, massive surge in plug-in hybrid imports. Furthermore, academic research conducted in France demonstrated that when specific EV models were excluded from national vehicle purchase subsidies, they suffered an immediate 60% sales decline relative to eligible counterparts. This stark divergence illustrates the profound influence that financial incentives exert on consumer behavior and underscores the risk that poorly calibrated protectionist policies could inadvertently suppress overall green vehicle adoption.
To navigate this complex trade dynamic, the Bruegel brief proposes a pragmatic diplomatic compromise: negotiating a temporary, managed trade agreement with China to cap the volume of electric cars and plug-in hybrids exported to the European market. Such a framework would provide European carmakers with a much-needed window of time to retool, optimize supply chains, and develop cost-competitive domestic EVs. The agreement would feature a strict sunset clause, with provisions for automatic escalation of trade restrictions should the agreed-upon caps be violated.
Historical precedents, however, suggest caution. Europe’s historical quota arrangements limiting Japanese automotive imports, alongside Canada’s recent restrictions on Chinese EV imports, demonstrate an inescapable economic trade-off: safeguarding domestic manufacturers almost universally translates to higher upfront acquisition costs for the consumer.
Broader Implications and Future Outlook
The policy choices made in Brussels over the coming months will define the trajectory of personal mobility and industrial competitiveness in Europe for a generation. The core tension remains unresolved: how to foster a resilient, localized green industrial ecosystem without penalizing the very consumers required to drive the green transition.
If battery localization mandates and low-carbon material rules are implemented without robust complementary subsidies or structural efficiency gains, the financial fallout will land squarely on car buyers, particularly those shopping in the accessible, mass-market segments. Conversely, an unfettered influx of heavily subsidized foreign imports threatens to hollow out Europe’s foundational industrial base, risking millions of manufacturing jobs and long-term technological sovereignty.
As automotive executives, policymakers, and consumer advocates debate the path forward, the findings from Bruegel serve as a sobering reminder that industrial policy is never cost-free. Whether those costs are absorbed by public coffers through targeted subsidies or borne directly by motorists at the dealership remains the defining question for Europe’s electric vehicle future.